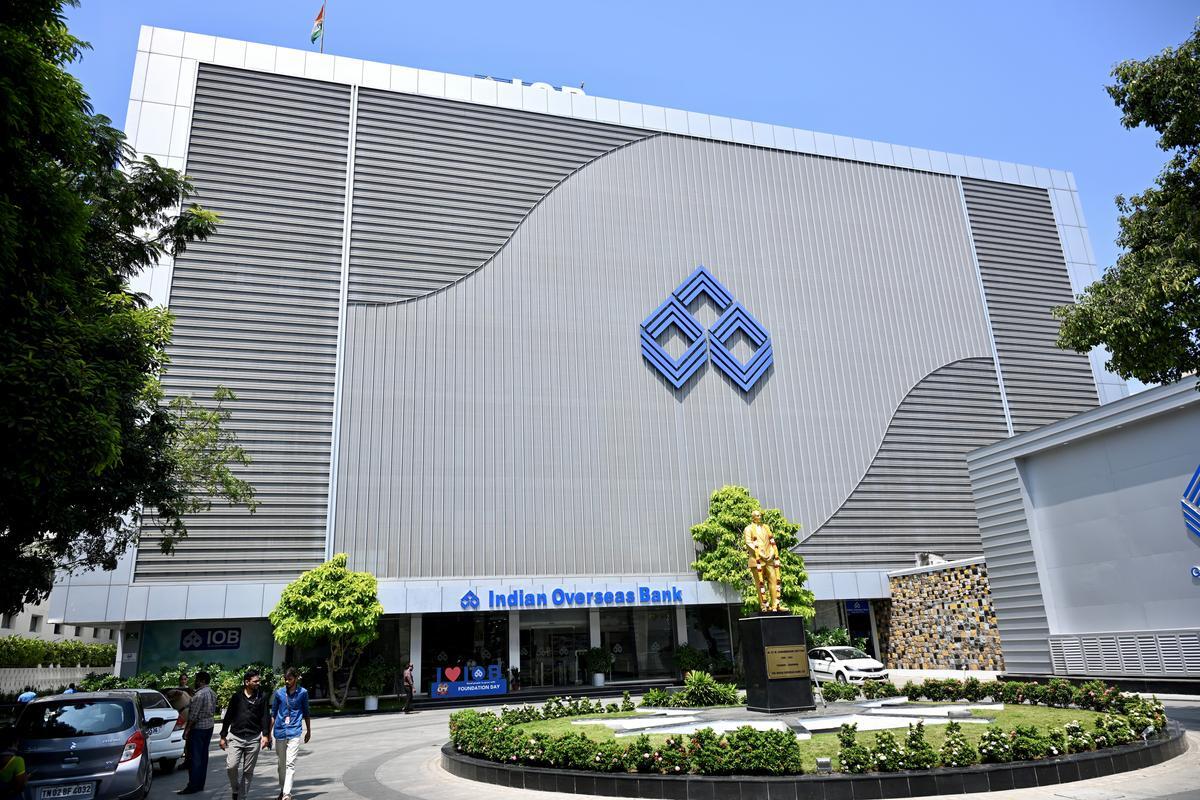
Chennai-based public sector lender Indian Overseas Bank (IOB) reported a 55.95% year-on-year increase in net profit to ₹1,912 crore for the second quarter of FY27, against ₹1,226 crore in the corresponding quarter last year, supported by strong net interest income growth, improving asset quality and expansion in advances.
Net interest income (NII) rose 26.41% year-on-year to ₹3,867 crore, indicating stronger income from the bank’s lending operations. Domestic net interest margin (NIM) improved by 14 basis points to 3.49%, while global NIM increased by 16 basis points to 3.37%.
The combination of higher interest income and improving asset quality strengthened profitability, with the bank also reporting gains in key return ratios.
Profitability improves alongside operating efficiency
IOB’s return on assets (ROA) increased by 33 basis points year-on-year to 1.53%, while return on equity (ROE) rose by 463 basis points to 24.58%.
The cost-to-income ratio improved by 498 basis points to 40.78%, indicating better operating efficiency as income growth outpaced the relative burden of operating expenses.
The improvement in these indicators suggests that the lender’s earnings growth is being accompanied by stronger returns on its asset and equity bases.
Gross NPA falls to 1.19%
Asset quality continued to strengthen, with the gross non-performing asset (NPA) ratio declining by 64 basis points year-on-year to 1.19%. The net NPA ratio fell by 12 basis points to 0.16%.
The slippage ratio declined by four basis points to 0.07%, while credit cost eased by one basis point to 0.17%.
IOB recovered ₹647 crore from NPAs during the quarter, equivalent to 2.95 times its quarterly slippages. This recovery provided additional support to the bank’s asset quality position.
The lower NPA ratios and credit costs are significant for profitability because reduced bad-loan formation and provisioning requirements can help preserve earnings.
Advances drive business expansion
IOB’s global business increased 22.05% year-on-year to ₹7,53,078 crore, reflecting growth in both lending and deposits.
Global advances grew 24.35% to ₹3,45,650 crore, outpacing the 20.16% increase in global deposits to ₹4,07,428 crore. The faster growth in advances indicates a stronger deployment of funds into lending, although its sustainability will depend on deposit mobilisation and margins.
The retail, agriculture and MSME (RAM) segment expanded 34.51%. Within the segment, agriculture advances grew 47.31%, retail advances increased 33.77%, and MSME advances rose 13.80%.
Global CASA deposits increased 20.73% to ₹1,65,862 crore. The domestic CASA ratio stood at 41.14%, while the global ratio was 40.71%.
Savings bank deposits rose 18.11% to ₹1,31,408 crore, while current account deposits increased 31.87% to ₹34,454 crore.
Capital position remains comfortable
The bank’s capital adequacy ratio (CRAR) improved by 66 basis points year-on-year to 18.60%, with the Common Equity Tier 1 (CET-1) ratio at 16.26%.
The capital position provides a buffer to support further lending growth. Going forward, sustaining margins, containing credit costs and maintaining deposit growth will be important for IOB to build on its strong earnings performance